Recessions are scary — headlines scream, portfolios shrink, and the instinct to sell everything is powerful. But for long-term investors, recessions have historically been among the best times to build wealth. The key is having a plan before fear takes over. Here’s how to invest intelligently when the economy contracts.
First: Understand What a Recession Means for Markets
A recession is typically defined as two consecutive quarters of declining GDP (the NBER uses a broader definition involving employment, income, and production). Markets usually fall before the recession is officially declared and often begin recovering before it ends — which is why waiting for “the all-clear” usually means missing the rebound.
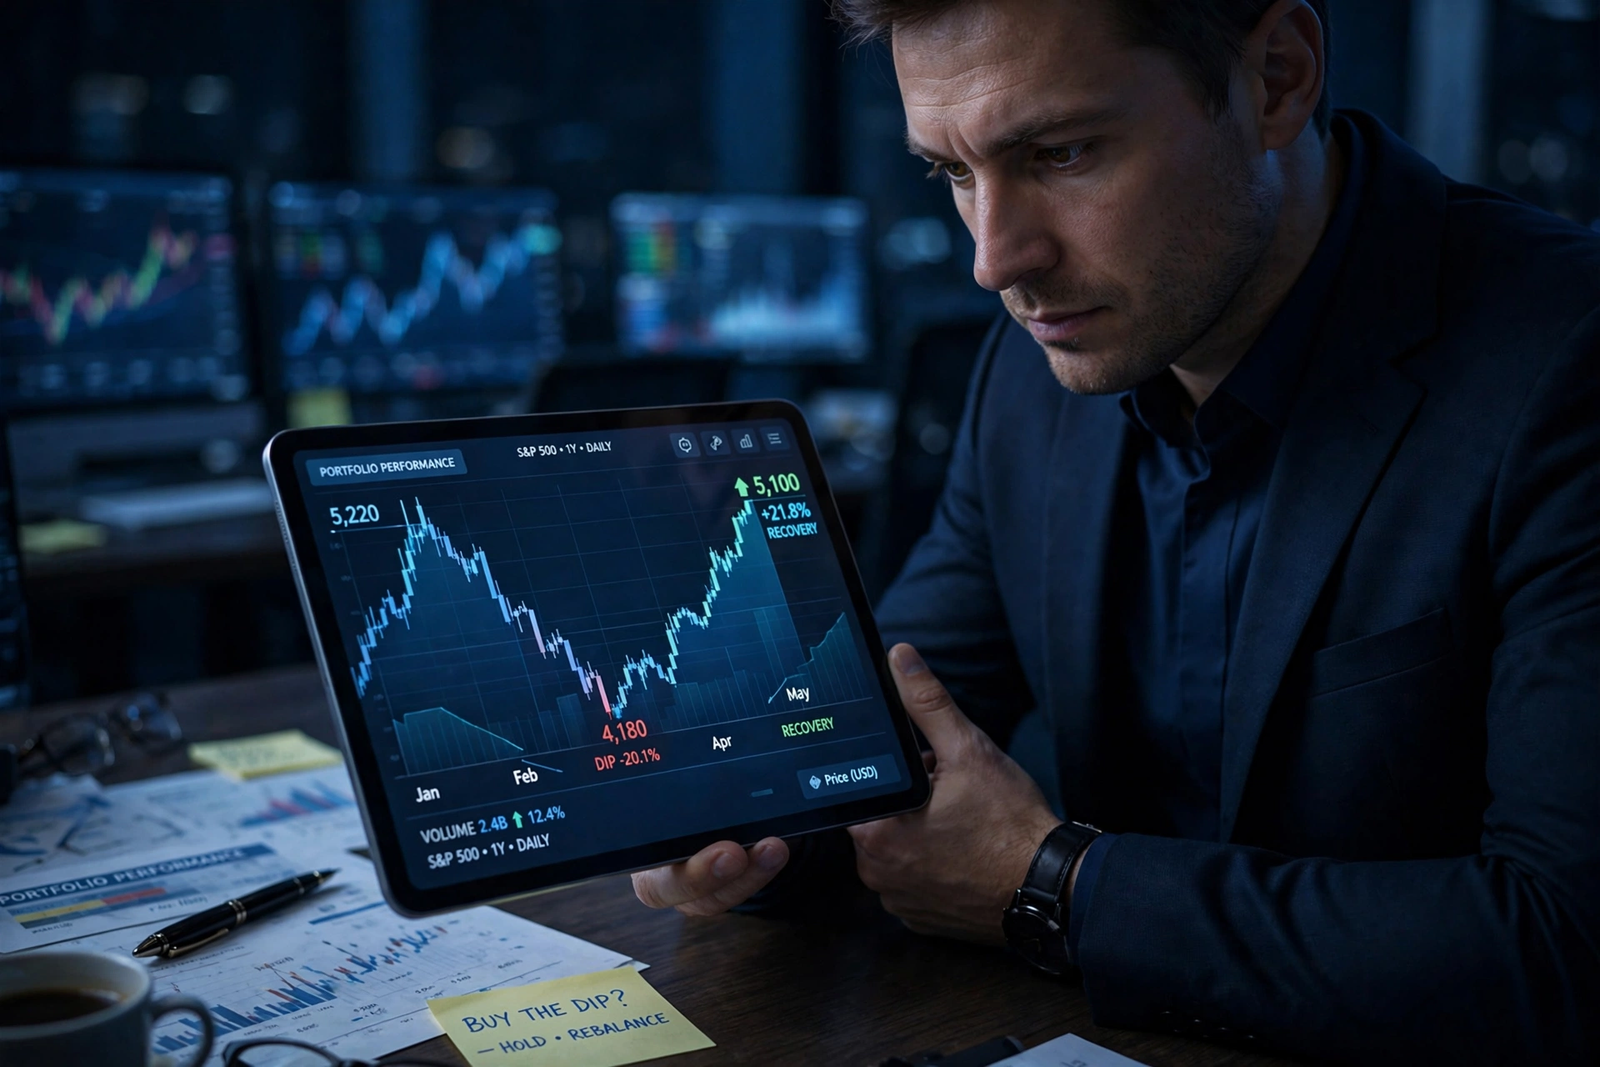
Historical perspective matters: the S&P 500 has recovered from every recession in modern history, including the Great Depression, the 2008 financial crisis, and the 2020 COVID crash. The average bear market lasts around 9–14 months; the average bull market lasts years.
Step 1: Secure Your Foundation First
Before investing a dollar in a downturn:
- Emergency fund intact: 3–6 months of expenses in safe savings — this is what prevents forced selling at market bottoms. See how many savings accounts should i have for structuring it.
- High-interest debt under control: Paying 24% on how credit cards work balances beats any market return
- Stable income or backup plan: Recessions bring layoffs; know your runway
Step 2: Keep Investing Consistently (Dollar-Cost Averaging)
The single most powerful recession strategy is boring: keep buying on schedule. When prices fall, your fixed contribution buys more shares. When markets recover, those cheap shares drive outsized gains.
Example: $500/month buys 5 shares at $100. If the market drops 30%, the same $500 buys ~7.1 shares at $70. When prices recover to $100, those shares are worth $710 — a 42% gain on that month’s contribution.
If you have a 401(k) or IRA, do not pause contributions during a recession unless you’ve lost income. Pausing is the most common and most costly mistake.
Step 3: Favor Quality and Defense
Consider tilting toward resilience:
- High-quality companies: Profitable businesses with strong balance sheets and low debt survive downturns; speculative, unprofitable companies often don’t
- Defensive sectors: Healthcare, consumer staples, and utilities historically hold up better than tech and luxury goods
- Bonds and Treasuries: High-quality bonds often rise when stocks fall, cushioning portfolios — check current yields at the U.S. Treasury’s official site
- Dividend aristocrats: Companies with 25+ years of rising dividends signal durable cash flow
Step 4: Rebalance, Don’t Panic-Sell
If stocks fell and bonds held steady, your allocation drifted conservative — rebalancing means buying stocks low to restore your target mix. This disciplined buying-low is exactly what most investors fail to do emotionally.
Set a rebalancing schedule (quarterly or semi-annually) and follow it mechanically.
Step 5: Look for Opportunities (Carefully)
Recessions create genuine bargains — but “cheap” can get cheaper:
- Tax-loss harvesting: Sell losers to offset gains, then buy similar (not identical) assets — bank the tax benefit
- Roth conversions: Converting traditional IRA funds to Roth when balances are depressed means less tax on the conversion
- Quality at discount: Great companies don’t stay on sale forever; nibble at positions you’d want to own for a decade
Mistakes to Avoid
- Panic selling: Locking in losses is the cardinal sin — the market’s best days often cluster near its worst
- Trying to time the bottom: Even professionals fail at this consistently
- Going all-in on “recession-proof” fads: Gold, crypto, and penny stocks all carry their own risks
- Overconcentration: Betting everything on one sector or stock
- Ignoring your risk tolerance: If you can’t sleep, your allocation was too aggressive — adjust after recovery, not during panic
For foundational investing knowledge, review the SEC’s investor education resources and consider whether the Bogleheads’ long-term investing philosophy fits your temperament.
Frequently Asked Questions
Should I stop investing during a recession?
No — for long-term investors, stopping is one of the worst moves. Continued investing through downturns (dollar-cost averaging) historically produces superior returns versus pausing and trying to re-enter later.
What investments do best in a recession?
Historically: high-quality bonds, Treasury securities, defensive sectors (healthcare, staples, utilities), and cash (for optionality). No asset is guaranteed — diversification remains essential.
Is it good to buy stocks during a recession?
For long-term investors, yes — recessions offer lower prices on quality assets. The key is buying consistently and diversely, not betting everything on a single “bottom.”
How long do recessions usually last?
U.S. recessions since WWII have averaged about 10–11 months. Bear markets (20%+ stock declines) average roughly a year. Recoveries have always followed — though the timeline varies.
Should I move everything to cash during a recession?
Almost never advisable. Cash loses purchasing power to inflation, and mistiming re-entry is extremely costly — missing just the 10 best market days in a decade can cut total returns roughly in half.