Quick answer: Sezzle Spend is a feature that lets you use your Sezzle buy-now-pay-later account to shop anywhere Visa is accepted, not just at Sezzle partner stores. It works through a virtual card in the Sezzle app: your purchase is split into 4 interest-free payments over 6 weeks, with the first 25% due at checkout. Availability depends on your Sezzle approval and spending power.
Sezzle built its name on buy-now-pay-later (BNPL) checkout buttons at partner retailers. Sezzle Spend breaks those walls down, turning your Sezzle account into a general-purpose payment method. Here is how it works, what it costs, and whether it is a smart way to pay.
What Is Sezzle Spend?
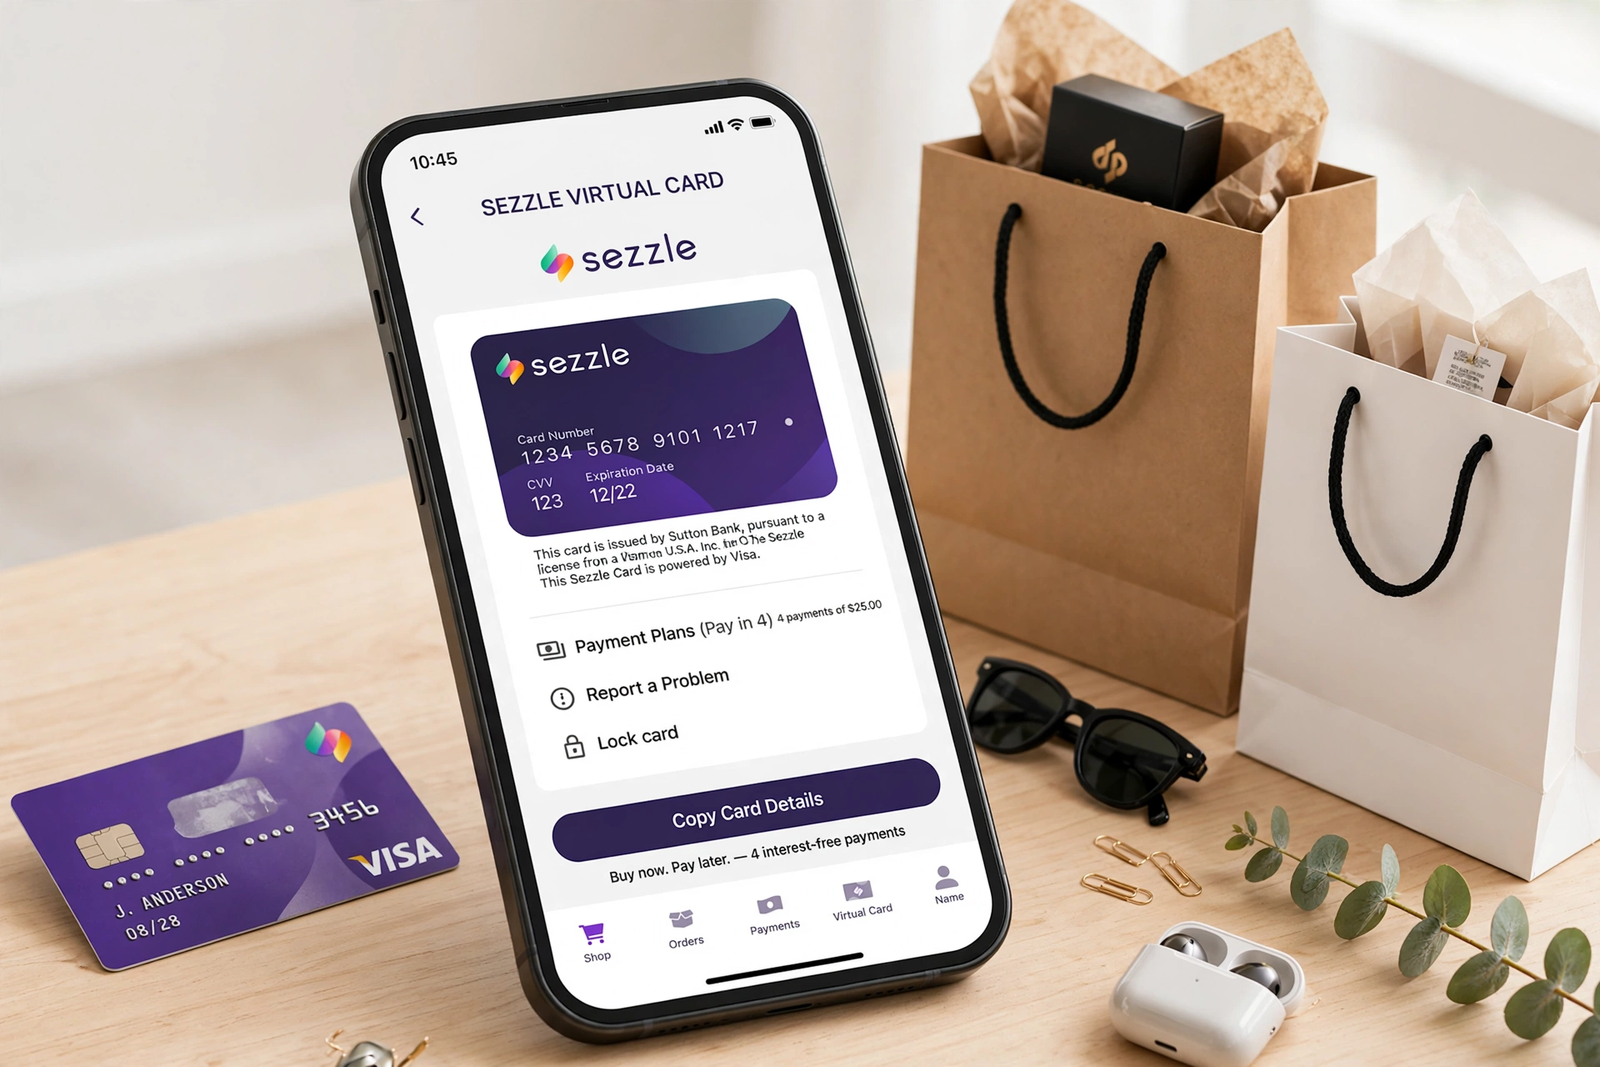
Traditionally, Sezzle only worked at checkout on participating merchants’ websites. Sezzle Spend extends that to virtually any online or in-store purchase through a single-use virtual Visa card generated in the Sezzle app.
The mechanics are the same as standard Sezzle:
- Your purchase is split into 4 equal payments over 6 weeks
- The first installment (25%) is due at checkout
- The remaining three payments are auto-charged every 2 weeks
- No interest if you pay on time
For example, a $200 purchase costs $50 today, then $50 in two weeks, $50 in four weeks, and $50 in six weeks.
How to Use Sezzle Spend: Step by Step
- Open the Sezzle app and check your available Spending Power, the maximum Sezzle will approve you for. This varies by user and payment history.
- Tap Sezzle Spend (or the virtual card option) in the app.
- Enter the purchase amount. Sezzle generates a single-use virtual Visa card number for that exact amount.
- Use the virtual card at any online checkout that accepts Visa, or add it to Apple Pay / Google Pay for in-store tap-to-pay.
- Pay 25% upfront from your linked debit card or bank account.
- Make the remaining payments on schedule through the app. Enable autopay to avoid late fees.
Sezzle Spend vs. Regular Sezzle: Key Differences
| Feature | Regular Sezzle | Sezzle Spend |
|---|---|---|
| Where it works | Partner merchants only | Anywhere Visa is accepted |
| How you pay | Checkout button | Virtual card in app |
| Payment structure | 4 payments / 6 weeks | 4 payments / 6 weeks |
| Credit check | Soft check only | Soft check only |
Fees and Costs
- Interest: $0 when you pay on schedule. Sezzle’s core product is interest-free.
- Late fees: Up to $10 per missed installment in most states (capped by state law; some states prohibit them). Failed payments can also trigger rescheduling fees.
- Sezzle Premium: Some features, including higher spending power and access to non-partner spending, may require Sezzle’s paid subscription tiers. Check the current plans in the app, as offerings change.
- No hard credit inquiry: Sezzle uses soft checks, so applying does not hurt your credit score. However, missed payments may be reported and damage your credit.
The Consumer Financial Protection Bureau has noted that BNPL products deserve the same careful cost comparison as credit cards; read their BNPL guidance before making it a habit.
Pros and Cons of Sezzle Spend
Advantages
- Interest-free installment payments anywhere Visa works, not just partner stores
- No hard credit check to get started
- Useful for smoothing large necessary purchases across paychecks
- Virtual card works online and in-store via mobile wallets
Disadvantages
- Encourages overspending: Splitting payments makes expensive purchases feel cheaper, the core risk of all BNPL. A solid how to budget money“>monthly budget is essential.
- Late fees add up if you miss installments across multiple concurrent plans
- No credit-building benefit in most cases; on-time payments typically are not reported to bureaus
- Spending power limits are often modest for new users ($100-$500) until you build history
- Refund complications: Returns on virtual-card purchases can take weeks to process through Sezzle’s system
Sezzle Spend vs. Alternatives
- Credit cards: Offer rewards, purchase protection, and credit building, but charge 20%+ interest if you carry a balance. Learn how credit cards work“>how credit cards work to compare fairly.
- Afterpay / Klarna: Similar BNPL mechanics; Klarna also offers a virtual card (Klarna Card). Compare fee structures and merchant acceptance.
- PayPal Pay in 4: Works anywhere PayPal is accepted; similar 4-payment structure.
- Saving up first: For non-urgent purchases, waiting 6 weeks and paying outright beats any BNPL plan. Our guide on how to get 1000 dollars fast“>getting $1,000 fast covers legitimate quick-cash options for genuine needs.
Is Sezzle Spend Safe?
Sezzle is a legitimate, publicly traded company and a certified B Corporation. The virtual card uses standard Visa network protections. The real risk is not fraud but behavioral: BNPL users consistently spend more than they would with cash or debit. Rules for safe use:
- Only use it for planned purchases already in your budget
- Never stack multiple BNPL plans you cannot track
- Keep total BNPL obligations under 10% of monthly take-home pay
- Enable autopay from an account that will have funds on due dates
FAQs
Does Sezzle Spend require a credit check?
Only a soft credit check, which does not affect your score. Approval is based on your Sezzle history, linked payment method, and their internal risk assessment rather than your FICO score.
Can I use Sezzle Spend in physical stores?
Yes. Add the generated virtual card to Apple Pay or Google Pay and tap to pay anywhere Visa contactless is accepted, subject to your spending power limit.
What happens if I miss a Sezzle payment?
You will be charged a late fee (up to $10 per installment in most states), future spending power may be reduced, and persistent non-payment can be sent to collections and reported to credit bureaus.
Can I pay off Sezzle early?
Yes. You can pay remaining installments early in the app at no penalty, which frees up spending power for new purchases.
Does Sezzle report to credit bureaus?
Sezzle may report delinquent accounts, but on-time payments are generally not reported, so it does not help build credit the way a credit card does.
Is there a minimum or maximum for Sezzle Spend?
Limits depend on your individual spending power, which grows with successful repayment history. New users often start around $100-$500; established users can access $1,000+. The virtual card is generated for a specific purchase amount.