A pre-approval letter is your golden ticket in the home-buying process — it tells sellers you’re a serious, qualified buyer. But it’s not open-ended. Understanding its lifespan helps you time your house hunt and avoid the frustration of an expired letter mid-negotiation.
Standard Pre-Approval Validity Periods
- Most lenders: 60–90 days
- Some lenders: 30 days (less common) or up to 120 days
- USDA and VA loans: Often follow the same 60–90 day window, though the underlying eligibility doesn’t expire
The expiration date should be printed on your pre-approval letter. If it isn’t, ask your loan officer.
What Can Invalidate a Pre-Approval Early
Your pre-approval is based on a snapshot of your finances. These changes can void it before the expiration date:
- New debt: Financing furniture, a car, or running up how credit cards work balances changes your debt-to-income ratio
- Job change: Switching employers, going part-time, or becoming self-employed — lenders may re-verify employment before closing
- Credit score drop: Late payments or new hard inquiries can drop you below program minimums
- Large unexplained deposits: Lenders must source large deposits; undocumented cash can derail underwriting
- Interest rate changes: A significant rate spike could change what you qualify for
The rule while house hunting: change nothing financial. Don’t open new credit, don’t close old accounts, don’t make large purchases, don’t move money around unusually.
Pre-Approval vs. Pre-Qualification
- Pre-qualification: A rough estimate based on self-reported info — quick, no credit check, carries little weight with sellers
- Pre-approval: Verified income, assets, and credit — a conditional commitment that sellers take seriously
Always get the pre-approval. In competitive markets, offers without one are often ignored.
How to Renew an Expired Pre-Approval
- Contact your loan officer before it expires if you’re still searching
- Provide updated pay stubs and bank statements (usually the last 30 days)
- The lender runs a fresh credit check (a new hard inquiry)
- If nothing material changed, renewal takes 1–3 days
- If rates or your finances changed, your approved amount may adjust up or down
Timing Your Pre-Approval
- Don’t get pre-approved too early. If you’re 6 months from buying, wait — each pre-approval involves a hard credit inquiry
- Do get pre-approved before touring homes seriously or making offers
- Consider shopping lenders within a 14–45 day window so multiple inquiries count as one for credit scoring
- Budget for the full process: Pre-approval (60–90 days) → offer accepted → how long after appraisal to close (typically 30–45 more days)
What Sellers See in Your Letter
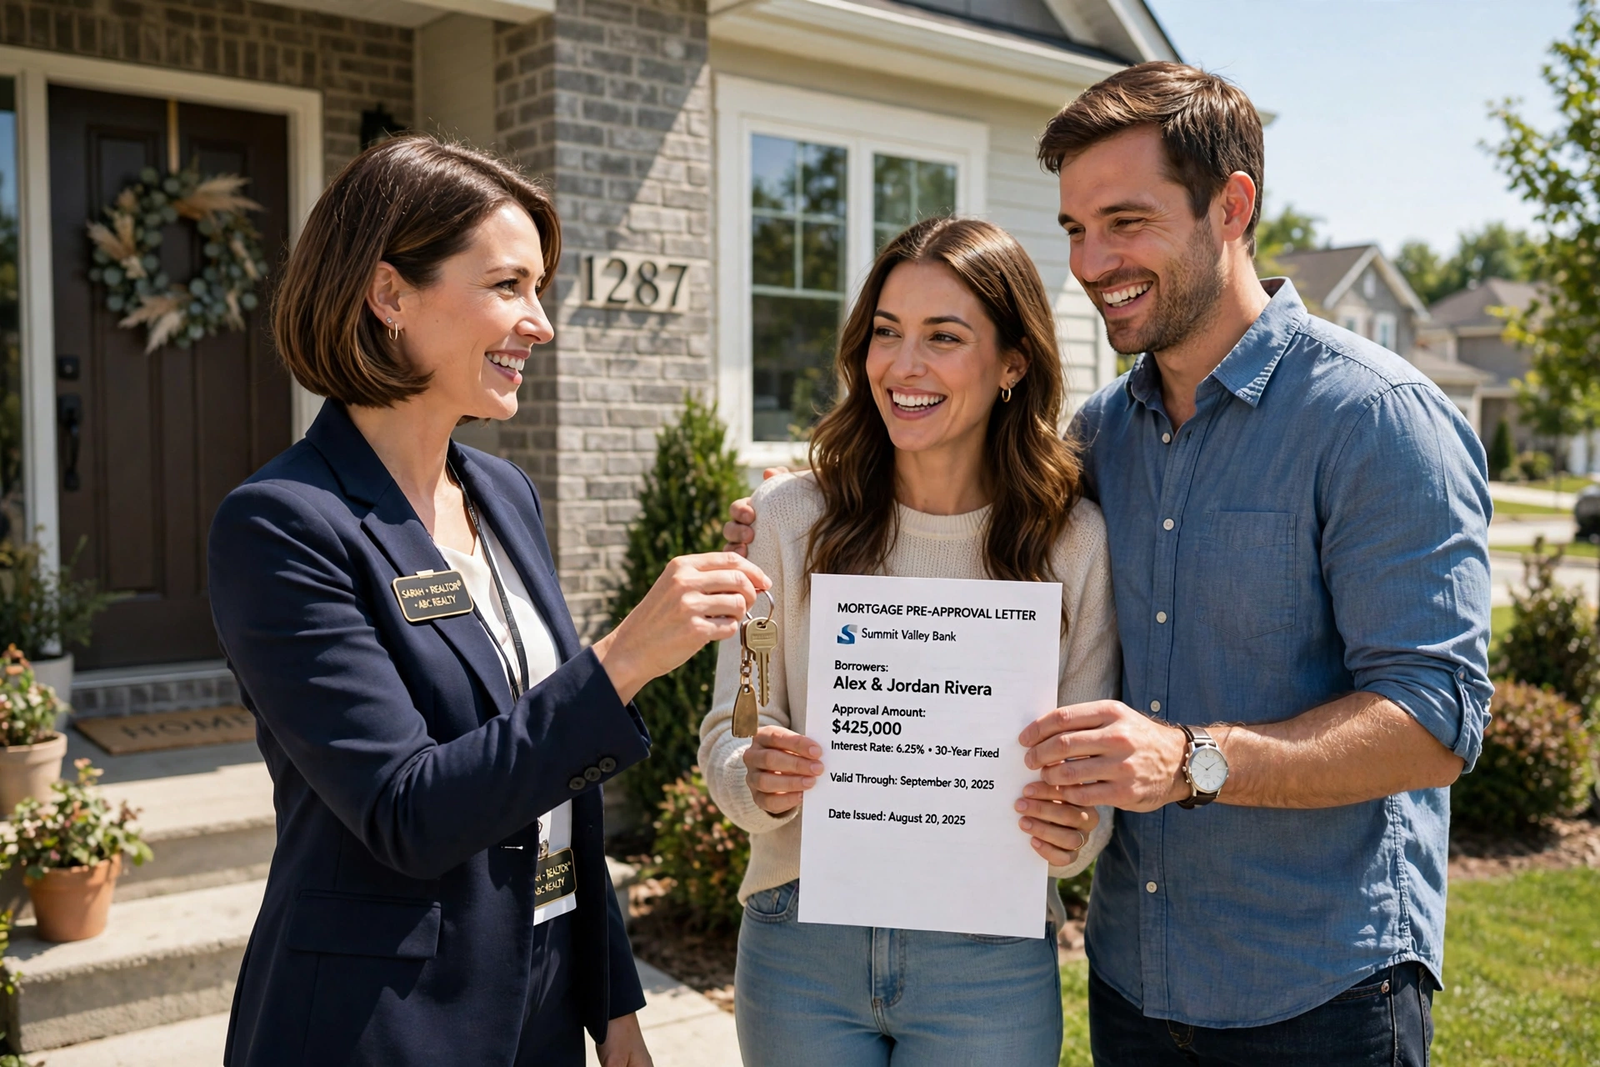
A strong pre-approval letter includes: loan amount, loan type, expiration date, and lender contact info. Some buyers ask lenders to write the letter for the offer amount rather than the maximum — avoiding showing sellers exactly how high you can go.
Saving for the purchase? See how to save for a down payment on a house and our guide to mortgage pre-approval basics from the CFPB. For FHA specifics, review HUD’s homebuying resources.
Documents You’ll Need for Pre-Approval
Having these ready speeds up the process considerably:
- Income: Last 30 days of pay stubs, W-2s for the last 2 years, federal tax returns for 2 years
- Assets: Bank statements (2–3 months) for checking, savings, and investment accounts
- Debts: Statements for car loans, student loans, credit cards — the lender pulls credit too, but having them helps
- ID: Driver’s license or passport, Social Security number
- If self-employed: 2 years of personal and business tax returns, profit-and-loss statement, possibly 1099s
- Other: Divorce decrees (alimony/child support), gift letters if using gift funds, landlord contact if renting
Rate Locks and Pre-Approval
Pre-approval and rate locks are separate things that buyers often confuse:
- Pre-approval confirms how much you can borrow — it doesn’t lock your interest rate
- Rate lock fixes your interest rate for a set period (typically 30–60 days) — usually done after your offer is accepted, not at pre-approval
- Some lenders offer extended or “lock and shop” programs that lock a rate while you house-hunt — ask if yours does
- If rates drop significantly between pre-approval and purchase, you benefit at final lock time; if they spike, your pre-approved amount could shrink
What Happens After Pre-Approval Expires Mid-Search
It’s common — the average buyer searches for 10+ weeks, right at the edge of the typical 60–90 day window. If your letter expires:
- Don’t panic — this is routine and sellers understand renewals
- Ask your lender for a renewal before making new offers
- Provide fresh pay stubs and bank statements
- If you’re mid-negotiation when it expires, tell your agent immediately so they can reassure the seller a renewal is in progress
- Consider getting pre-approved with a second lender as backup — useful if the first lender’s terms worsen
Frequently Asked Questions
Can I extend my mortgage pre-approval?
Yes — lenders routinely renew pre-approvals with updated documents and a fresh credit pull. If your finances are stable, it’s a 1–3 day process.
Does getting pre-approved hurt my credit?
It creates one hard inquiry (~5 points, temporary). Multiple mortgage inquiries within a 14–45 day shopping window count as a single inquiry in most scoring models.
Can a pre-approval be denied after being issued?
Yes. Pre-approval is conditional — final approval happens during underwriting. Job loss, new debt, appraisal issues, or undisclosed financial problems can all cause denial before closing.
Should I get pre-approved by multiple lenders?
Yes — comparing 3+ lenders can save you thousands through better rates and lower fees. Do it within a focused 2–3 week window to minimize credit impact.
Does pre-approval guarantee I’ll get the mortgage?
No. It’s a strong conditional commitment, not a guarantee. Final approval depends on underwriting verification, appraisal, title, and your finances remaining stable through closing day.