The 40-page business plan is dead — nobody reads it, including the people who ask for it. Writing a simple business plan for a small startup in 2026 means a one-page lean plan you can draft in an afternoon, covering: the problem, your solution, customers, how you’ll make money, and what you need. That’s the document that actually guides decisions.
I’ve written plans that raised money and plans that gathered dust. The difference was never length — it was clarity. Here’s the practical method.
The One-Page Plan (Start Here, Maybe End Here)
For most small startups, this is the entire plan. Nine boxes, one page:
- 1. Problem: what painful, specific problem do customers have? (One or two sentences. If you can’t state it simply, you don’t understand it yet.)
- 2. Solution: what you sell that fixes it — and why it’s 10x better than current alternatives, not 10% better.
- 3. Target customers: specific — “busy parents in suburbs” beats “everyone.” Name the first 10 customers you could call today.
- 4. Value proposition: the one-line reason to buy. If it takes a paragraph, keep editing.
- 5. Revenue model: how money flows — price, what they pay for, how often. Be specific: “$49/month subscription” not “SaaS revenue.”
- 6. Costs: the big ones — what will you spend monthly to operate? Honest numbers, not hopes.
- 7. Marketing: how the first 100 customers find you. “Social media” isn’t a channel — “Instagram reels targeting local moms” is.
- 8. Milestones: what must be true in 3, 6, 12 months? Concrete, measurable.
- 9. Funding needed: how much to reach the first milestone, and what it’s spent on.
This is the Lean Canvas format (adapted from Ash Maurya’s work) — use the free template at leanstack.com or just draw nine boxes on paper. An afternoon’s work that forces every hard question.
The Sections Banks and Investors Actually Read
If you need a loan or investment, expand the one-pager into a short traditional plan (10-15 pages max). Know what readers skim for:
- Executive summary (write last, read first): one page — the business, the ask, the return. If this doesn’t hook them, nothing else matters.
- Market analysis: how big is the market, really? Use bottom-up math (“2,000 potential customers × $50 = $100k market”) not top-down fantasy (“it’s a $10B industry and we’ll get 1%”). Lenders see through top-down instantly.
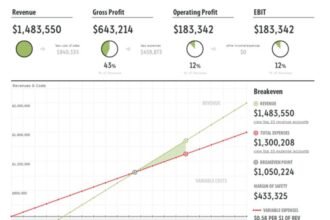
- Financial projections: 3 years of revenue, costs, profit — monthly for year 1. Banks care about cash flow (can you make loan payments?); investors care about growth rate. Label assumptions explicitly.
- The team: why are you the person to do this? Relevant experience beats credentials — “10 years as a bakery manager” sells a bakery loan better than an MBA.
- The ask: exactly how much, exactly what for, exactly how it gets repaid/returned. Vagueness here kills deals.
What they skip: your 5-page company history, the 20-slide competitor matrix, adjectives. Numbers and specifics win; fluff loses.
Financial Projections Without Lying to Yourself
The hardest section, and the most important to do honestly:
- Start with costs, not revenue. Costs are knowable (rent, salaries, materials); revenue is a guess. Build the cost base first — it sets your break-even target.
- Three scenarios: conservative, expected, optimistic. If the business only works in the optimistic case, rethink the business.
- Cash flow > profit. You can be “profitable” and broke — if customers pay in 60 days but rent is due monthly, you have a cash-flow gap. Map when money moves, not just totals. Cash-flow management is the skill that keeps startups alive.
- Include your salary. “I’ll take nothing for a year” isn’t a plan, it’s a hope. Pay yourself something real in the projections — investors and banks both discount founder-martyr math.
- Sanity-check against comparables: find revenue figures for similar businesses (industry reports, franchise disclosure documents, asking owners). If your projection is 5x the industry average, explain why specifically.
Free tools: SCORE’s financial templates, the SBA’s business plan tool, and Wave/QuickBooks for ongoing tracking once live.
Validating Before You Write (the Step Everyone Skips)
A plan built on untested assumptions is fiction. Before finalizing:
- Talk to 20 potential customers. Not friends — strangers with the problem. Ask about their current workaround and what they’d pay. If 15+ won’t pay, the plan needs surgery, not formatting.
- Test the price: “Would you pay $X?” gets polite lies. Pre-orders, deposits, or letters of intent get truth. Even 5 pre-sales validate more than 50 surveys.
- Price your costs with real quotes: call suppliers, landlords, insurers. Spreadsheet guesses are always 30% low — real quotes hurt less now than later.
- Run a tiny pilot: sell to 10 customers manually before building anything. The learnings rewrite the plan — that’s the point.
The plan is a hypothesis document, not a promise. The best founders treat it as version 1.0, update it quarterly, and aren’t embarrassed when reality edits it. A plan that never changes is a plan nobody’s using.
Free Templates and When to Get Help
- SBA Business Plan Tool (sba.gov) — free, guided, lender-respected format.
- SCORE templates — free Word/Excel templates plus free mentoring from retired executives. Criminally underused; find your local chapter.
- Lean Canvas (leanstack.com) — the one-page format above.
- LivePlan / Bizplan — paid ($15-$30/month), worth it if financial projections intimidate you — they walk through the math.
- When to hire help: if seeking $100k+ in loans/investment, a $500-$2,000 professional review (SCORE mentor free, consultant paid) catches the holes investors will poke. Cheap insurance.
- SBDCs (Small Business Development Centers) — free, government-funded advising in every state. Business plan reviews are literally their job.
Start with the one-page canvas this weekend. Expand only if someone with money asks for more. And remember getting your first customers — the plan gets you ready; customers keep you alive. The SBA’s business plan guide is the definitive free resource.
Keep Reading
If this was useful, you might also like cash-flow management and getting your first customers.
The Bottom Line
Write the one-page lean plan first — problem, solution, customers, revenue, costs, marketing, milestones, funding. Expand to 10-15 pages only for lenders/investors, leading with financials and the ask. Validate with 20 customer conversations and real cost quotes before finalizing, use SCORE/SBDC free help, and treat the plan as a living hypothesis — update it quarterly as reality teaches you.
Frequently Asked Questions
How long should a business plan be?
One page for yourself (lean canvas). 10-15 pages for banks/investors. Anything longer isn’t read — I guarantee the 40-page plan gathers dust while the one-pager gets used weekly.
Do I need a business plan to get a small business loan?
Yes — banks require one, and they focus on financial projections (especially cash flow proving you can service the loan) and your experience. The SBA’s format is what loan officers expect to see.
What’s the difference between a business plan and a business model canvas?
The canvas (one page) is a working hypothesis for founders — fast, visual, iterative. The traditional plan is a communication document for outsiders (lenders, partners). Start with the canvas; expand as needed.