Kids absorb money habits the way they absorb language — by watching you, long before anyone sits them down for a lesson. By age 7, most children have already formed basic money behaviors that persist into adulthood. That’s either terrifying or empowering, depending on how you look at it. The good news: teaching kids good money habits early doesn’t require lectures, allowances spreadsheets, or being a finance expert. It requires small, consistent, age-appropriate experiences with real money.
I’ve watched friends raise both money-confident and money-anxious kids, and the difference was never income — it was whether money was a normal, talked-about, hands-on part of childhood. Here’s how to make it normal.
The Foundation: Talk About Money (Normally)
The biggest mistake isn’t teaching the wrong things — it’s teaching nothing. In many families, money is secret, stressful, or simply never discussed. Kids fill the silence with their own stories, usually anxious ones. You don’t need to share your salary; you need to narrate decisions out loud:
- “We’re choosing the store brand because it tastes the same and costs less — that’s smart shopping.”
- “We’re waiting to buy that until next month because we’re saving for vacation first — that’s prioritizing.”
- “This costs $40. That’s about 4 hours of work. Is it worth it to you?” (For older kids — the hours-of-work frame is powerful.)
Normalizing money talk removes both the mystique and the anxiety. Money becomes a tool you discuss, not a secret you stress about.
How Can I Teach My Kids Good Money Habits Early? By Age
Ages 3–5: Money exists and has limits
- Use cash for small purchases in front of them — tangible money teaches better than invisible cards at this age
- Play store at home — buying, selling, making change (it’s play, but the concepts stick)
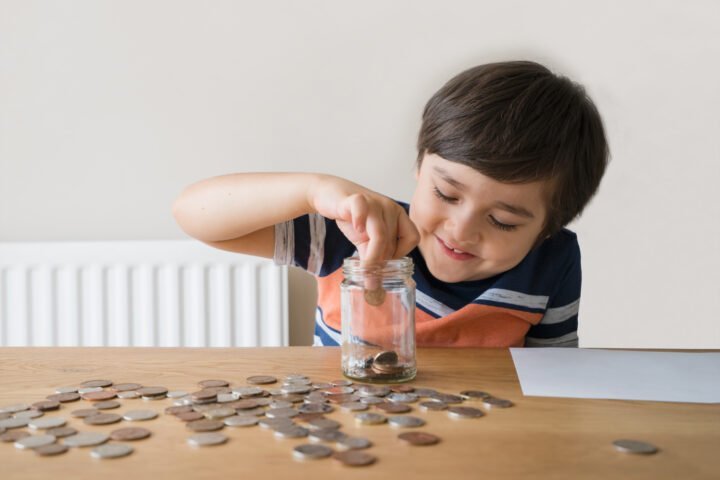
- The three jars: Spend, Save, Share. Any money they get (gifts, tooth fairy) splits three ways. The physical jars make abstract concepts concrete.
- “We can’t afford it” → try “that’s not in our plan right now.” The first teaches scarcity; the second teaches prioritizing.
Ages 6–9: Earning, choosing, and waiting
- Allowance tied to… nothing? Or chores? Honest debate here. My take: a small base allowance (teaches budgeting) plus paid extra chores (teaches earning). Required family contributions (clean your room) stay unpaid — that’s citizenship, not employment.
- Let them make small purchases with their own money — and let them make mistakes. The $8 toy that breaks in a day teaches more than any lecture about value.
- Introduce waiting: “If you still want it in two weeks, we’ll get it.” Most wants evaporate — the lesson teaches itself.
- Start the savings goal visual: a chart on the fridge tracking progress toward something they want. Delayed gratification, made visible.
Ages 10–13: Budgeting and earning
- Give them real budget responsibility: back-to-school clothes budget, birthday party budget. Real money, real trade-offs, real learning.
- Encourage earning: yard work for neighbors, pet sitting, selling outgrown stuff. Earned money is valued differently than given money — the research on this is clear.
- Introduce the concept of interest: “If you save $100 for a year, I’ll add 10%.” (The Bank of Mom and Dad pays great rates.) Watch compound interest click in real time.
- Compare prices together while grocery shopping — unit prices, store brands, the whole game. Make it a treasure hunt.
Ages 14+: Real-world money
- A teen checking account with a debit card (many banks offer teen accounts with parental controls). Real statements, real overdraft lessons (better learned on $50 than $5,000).
- Part-time work when appropriate — the single best money teacher there is.
- Talk about credit: what it is, how interest works, why minimum payments are a trap. Before they turn 18 and the offers flood in.
- Introduce investing basics: a custodial Roth IRA for earned income is a genuinely life-changing gift. Show them compound growth projections — the numbers do the convincing.
The Habits That Matter Most
If you only instill a few things, make them these:
- Spend less than you earn. The entire game, in six words. Everything else is detail.
- Save first, not last. The three jars, then automatic transfers — “pay yourself first” as a reflex, not a struggle.
- Distinguish wants from needs — and respect that wants are okay, in budget.
- Money is a tool, not a score. Kids who tie self-worth to spending become adults who do the same. Model contentment visibly.
These pair with the broader household approach in saving money on everyday expenses — kids learn fastest when the whole family practices.
Model It (They’re Watching)
The uncomfortable truth: your money behavior is the curriculum. Kids who see parents budget calmly, discuss purchases openly, and handle setbacks without panic internalize financial confidence. Kids who see secret spending, money fights, or chronic stress internalize that instead. You don’t need to be perfect — narrating your own learning (“I impulse-bought this and regretted it — here’s what I’ll do differently”) is powerfully instructive. Imperfect honesty beats perfect silence.
The Allowance Conversation Script
Starting an allowance? Here’s how to frame it so it teaches instead of just distributing cash:
- The setup: “You’re getting [amount] a week. This isn’t payment for being part of the family — chores like cleaning your room are everyone’s job. This is your money to practice with.”
- The three jars: “Every dollar splits three ways: some to spend now, some to save for something bigger, some to share with others. You decide the split, but all three jars get something every time.”
- The rules: “Your spend jar is yours — no lectures on what you buy. But when it’s empty, it’s empty until next week. I’m not a bank.” (Then hold the line. The empty jar is the lesson.)
- The earning layer: “Want more than the base? These extra jobs pay [amounts]: [list 3–4 real tasks with real prices]. Available anytime.”
- The save jar goal: “What’s something you want that’s [4–8 weeks] of saving? Let’s put a picture of it on the jar and track progress.” (The visual goal is what makes delayed gratification concrete.)
- How much? A common rule: $1 per week per year of age ($8/week for an 8-year-old). Adjust to your budget — the amount matters less than the consistency.
Have this conversation once, then let the system run. Resist rescuing, resist lecturing — the jars do the teaching. Check in monthly: what’s working, what did you learn, any goal updates? That’s financial education.
The Takeaway
Teaching kids good money habits early means talking about money normally, giving them hands-on experience with real (small) amounts at every age, letting them make low-stakes mistakes, and modeling the behavior yourself. Start this week: get three jars, label them Spend/Save/Share, and narrate one money decision out loud. Small, consistent, and early — that’s the whole formula, and it works. For structured, age-by-age resources, the Consumer Financial Protection Bureau’s Money As You Grow program is excellent and free.